Fast Reading
- Global yields have risen sharply, driven by higher energy prices, resilient economic activity and growing fiscal pressures. We think changing expectations for central bank policy have been the largest contributor to the recent move.
- Markets are pricing a more aggressive central bank response to inflation than we think is justified. Without stronger second-round effects in core inflation, wages or inflation expectations, we expect less tightening than markets currently imply.
- For investors, we see the strongest opportunity in shorter and intermediate sovereign maturities, particularly the 2-to-5-year part of the yield curve, while remaining cautious on longer-dated bonds where fiscal and term-premium risks remain elevated.
Introduction
Global interest rates have risen sharply during this year’s third quarter, producing negative fixed income total returns. Year to date through September 30, 2026, the GBP-hedged Bloomberg Global Aggregate Index returned -1.44%: higher coupon income only partly offset capital losses from rising yields.
We think three primary forces have driven the increase in yields: higher energy and related prices, resilient economic activity led by the AI investment cycle and mounting pressure on government finances. The move also has two distinct components—changing expectations for central bank policy rates and a higher term premium—which typically affect different parts of the yield curve. Monetary policy expectations tend to be reflected most directly at the front end, while changes in term premium exert greater influence farther out the curve.
Source 1: Bloomberg, as of October 8, 2026
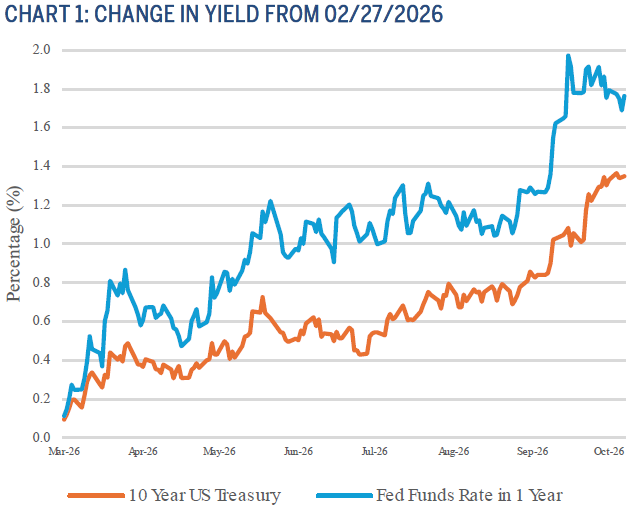
While market commentary has focused heavily on fiscal sustainability and central bank credibility, we think shifting expectations for policy rates explain most of the recent rise in yields. Chart 1 illustrates this dynamic in the United States:
since the start of the war in the Middle East, expectations for the overnight policy rate have risen by more than 10-year Treasury yields. Similar dynamics have emerged across other developed sovereign bond markets.
We believe the combination of today’s macroeconomic backdrop and current expectations for monetary policy has created a particularly attractive investment opportunity in fixed income. This paper first examines the forces pushing long-end term premiums higher, then turns to the drivers of front-end central bank expectations and finally considers how we are constructing portfolios to capitalise on what we view as a meaningful market dislocation.
Our conviction is considerably higher around the market pricing of monetary policy expectations than it is around forecasting the direction of term premium. That distinction is important. We think the current investment environment reinforces the case for separating these two sources of interest-rate risk within portfolio construction rather than treating duration as a single, undifferentiated exposure.
The Long End: Are 10-Year Yields Unusually High?
Long-term interest rates can be thought of as the average expected overnight policy rate plus a term premium—the additional yield investors demand for lending over longer periods.
That premium reflects a range of factors, including inflation volatility, central bank credibility, fiscal sustainability, political and institutional risk and imbalances between the supply and demand for bonds. We think several of these conditions are deteriorating across many developed sovereign bond markets and are likely to keep upward pressure on term premiums.
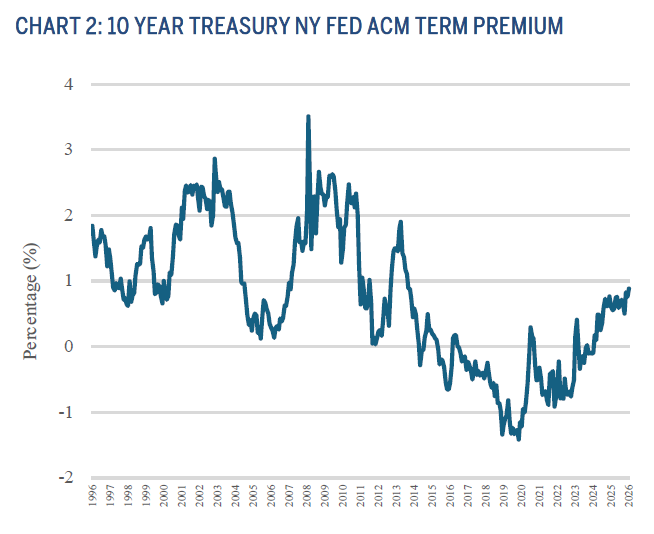
In the United States, the New York Federal Reserve’s widely cited ACM model estimated the 10-year Treasury term premium at 95 basis points as of October 8, 2026 (Chart 2). Although well above its post-Global Financial Crisis (GFC) average, that level remains far below the roughly 2% average recorded during the 20 years before 2007.
Source 2: New York Federal Reserve, Bloomberg as of October 8, 2026
We have written previously about the possibility that interest rate markets are returning to an “old normal” more consistent with the period before the GFC. We continue to think the increase in interest rates reflects, at least in part, a structural normalisation in interest-rate risk premia rather than a purely temporary or cyclical adjustment. Fiscal sustainability is likely to remain an important part of that normalisation. Absent meaningful fiscal consolidation, higher borrowing costs may ultimately be required to impose greater fiscal discipline on governments. Institutional and political risks also appear higher in the current environment. At the same time, geopolitics and AI create potentially inflationary forces, while the scale of AI-related capital investment could contribute to supply-demand imbalances through a crowding-out effect across global corporate and sovereign bond markets. Taken together, those factors leave us cautious on longer-maturity sovereign debt. We think long-term interest rates are more likely to settle closer to the ranges that prevailed before the GFC than to those experienced during the unusually low-rate period that followed.
The Front End: Markets Are Pricing an Aggressive Response
Shifting expectations for central bank policy have likely been the primary driver of this year’s rise in interest rates, particularly since the war in the Middle East disrupted energy and related markets.
Historically, central banks have tended to look through temporary supply shocks that monetary policy is poorly equipped to resolve. Markets are now pricing a more aggressive response.
Investors may believe that increasingly frequent shocks require greater policy intervention. They may also believe that central banks, having been criticized for responding too slowly to post-pandemic inflation, have become more sensitive to upside inflation risks.
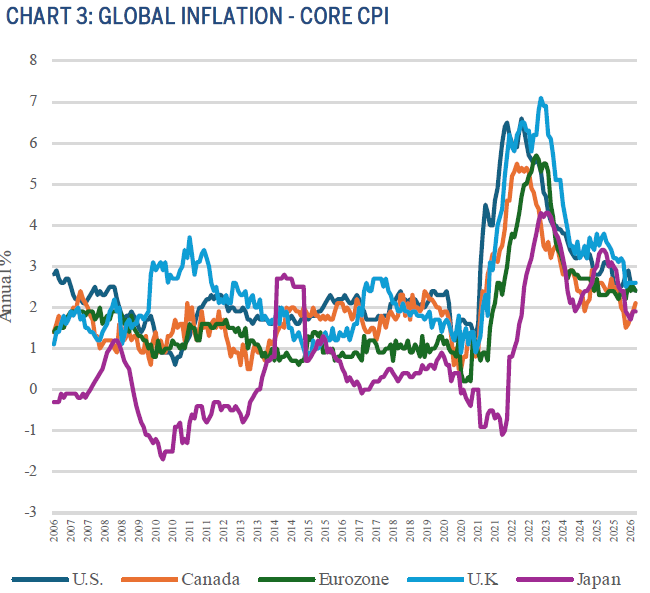
We disagree with that interpretation and, therefore, with the degree of tightening now embedded in market pricing. Consistent with central bank speeches, statements, interviews,
Source 3: U.S. BLS, Statistics Canada, Eurostat, U.K. ONS, Japan SBJ, Bloomberg as of October 8, 2026
and other communications, we believe aggressive tightening is generally inappropriate unless an energy shock produces meaningful second-round effects – for example, accelerating core inflation, stronger wage growth or de-anchored inflation expectations. Broadly, we have not seen those effects emerge (Chart 3).
Central banks have traditionally been reluctant to raise rates in response to higher energy prices because the same shock that lifts headline inflation also weakens economic growth. In our experience, the Federal Reserve has generally treated higher energy costs as a tax on consumers rather than a persistent source of inflation. More frequent shocks do not necessarily change that logic. Higher policy rates cannot end the conflict in the Middle East, expand commodity supply or increase refining capacity.
The current backdrop also differs substantially from the immediate post-pandemic environment. Growth and inflation are lower, unemployment is higher, wage growth is more subdued, fiscal stimulus is more limited, and policy rates are generally neutral-to-restrictive across developed markets. AI investment remains an important tailwind, but it sits within a broader economic environment that is considerably less inflationary than that which followed the pandemic.
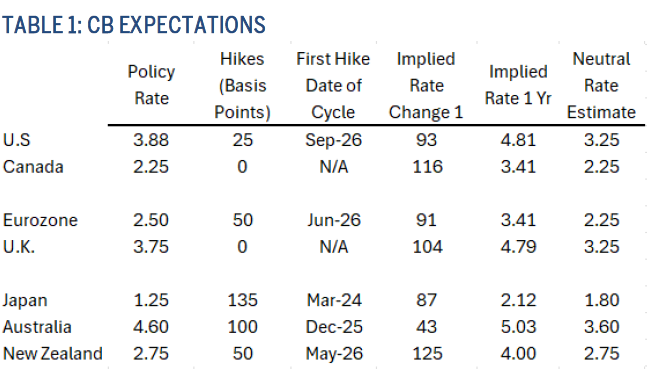
Source: Fed, BOC, ECB, BOE, BOJ, RBA, RBNZ, Bloomberg as of October 8, 2026
As the table here shows, several central banks have already tightened, while markets price substantial additional increases over the next year. If delivered, that path would push overnight
rates well above central banks’ estimates of neutral at the same time the underlying supply shock is weakening the growth outlook. That combination strikes us as increasingly difficult to justify.
Strategy Positioning
Our investment process compares our 12-month central bank forecasts with current market pricing to identify the most significant dislocations across global rates markets.
We expect less tightening than markets imply and, in some economies, rate cuts in 2027. We are therefore extending the strategy’s overall duration and concentrating exposure in the 2-to-5-year segments of sovereign yield curves, where we see the most attractive risk-adjusted return opportunities. Importantly, we are deliberately separating policy-rate risk from term-premium risk.
We believe policy expectations are too hawkish, while longer-dated term premiums face legitimate structural upward pressure. The 2-to-5-year sector therefore provides relatively clean exposure to a potential repricing of monetary policy expectations without taking as much of the fiscal, supply, and term-premium risks embedded farther out the curve.
This distinction is central to our current positioning. We are not making a broad call that all global yields should decline. Rather, we think there is a meaningful dislocation between the degree of tightening priced into shorter and intermediate maturities and that structural risks continue to justify caution farther out on the curve.
Our highest-conviction positions are outlined below and have generally come at the expense of our allocation to U.S. rates and credit risk. A common and important factor for our conviction that is implied across the sovereigns below is our view that fiscal policy is relatively healthier versus that of other developed-market sovereigns.
New Zealand
1Policy rates have risen by 50 basis points thus far this year, while markets price another 100 basis points of hikes over the next 12 months.
Yet considerable economic slack remains. Unemployment is 5.6%, its highest level since 2015. Higher energy costs will likely lift headline inflation, but we do not interpret the RBNZ’s guidance as supporting a move toward excessively restrictive policy levels. Further tightening is possible.
Even allowing for that risk, we think current market pricing is too aggressive.
Australia
2Policy rates have risen by 100 basis points this year, placing policy well above estimates of neutral and contributing to a material slowing of the economy. Unemployment has climbed from a post-pandemic low of 3.4% to 4.6%, a level the RBA associates with downward pressure on inflation. Home prices continue to decline year over year, while higher interest rates are squeezing real household incomes. We think these conditions reduce the need for the degree of additional tightening currently reflected in market pricing.
Canada
3Our conviction has increased, and we have expanded the position. Three factors support this view.
First, persistent U.S. pressure on the trade relationship has created significant uncertainty and downside risk to the Canadian economy that may persist through Donald Trump’s term.
Second, the Bank of Canada’s preferred measures of core inflation remain near 2.0%, suggesting limited second-round effects from higher energy prices.
Third, Bank of Canada Governor Tiff Macklem continues to emphasise excess economic slack, which should offset at least some of the inflationary pressure from energy.
Although the policy rate is already near the lower end of the Bank’s estimates of neutral, markets imply almost 100 basis points of additional hikes over the next 12 months. We think the Bank of Canada may not need to raise rates at all over that period.
Investment Implications
Market expectations for central bank rate increases have become excessive relative to our own forecasts, creating what we view to be one of the most attractive opportunities in global rates that we have experienced.
The AI investment cycle may have temporarily raised neutral interest rates, although by different amounts across countries and regions. Even so, we do not expect the energy and commodity shock caused by the war in the Middle East to create persistent upward pressure on global inflation unless it generates meaningful second-round effects.
At the same time, the normalisation in global yields has materially improved the prospective return available from fixed income.
Today's starting yields provide meaningful income if economic growth remains resilient or if inflationary pressures persist. At the same time, the excessive tightening currently priced into several markets creates the potential for meaningful capital appreciation if growth slows or inflation pressures fade.
Concentrating duration exposure in shorter and intermediate maturities allows us to pursue that opportunity while limiting exposure to the structural pressures we believe remain present farther out sovereign yield curves.
This is particularly important in an environment where equity and credit risks are increasingly exposed to a common factor: the continued strength of the AI investment cycle. If that cycle remains strong, today’s higher starting yields provide fixed income investors with meaningful income to absorb the risk of rising interest rates. If growth weakens or if the AI investment cycle slows, bonds have greater scope to provide the diversification benefits that investors have traditionally expected from the asset class.
For that reason, we think there may be no better time for a bond fund to behave like a bond fund – as a counterbalancing force within clients’ portfolios and a source of diversification against equity and credit risks.
As always, we are keen to debate these topics with our investors and would welcome your thoughts.
Portfolio Managers
CHRIS DIAZ, CFA Partner and Portfolio Manager GlobalMacro – Americas/Asia, Chicago
RYAN MYERBERG Partner and Portfolio Manager GlobalMacro – Europe/Asia, London
COLBY STILSON Partner, Head of Global Fixed Income and Portfolio Manager Global Credit, London
Endnotes
1Reserve Bank of New Zealand; Statistics New Zealand; Bloomberg market data. Data as of October 8, 2026. 2Reserve Bank of Australia; Australian Bureau of Statistics; Bloomberg market data. Data as of October 8, 2026. 3Bank of Canada; Statistics Canada; Bloomberg market data. Data as of October 8, 2026.
Disclosures
The views expressed are those of the author and Brown Advisory as of the date referenced and are subject to change at any time based on market or other conditions. These views are not intended to be and should not be relied upon as investment advice and are not intended to be a forecast of future events or a guarantee of future results.
The information provided in this material is not intended to be and should not be considered to be a recommendation or suggestion to engage in or refrain from a particular course of action or to make or hold a particular investment or pursue a particular investment strategy, including whether or not to buy, sell or hold any of the securities or funds mentioned. It should not be assumed that investments in such securities have been or will be profitable. To the extent that specific securities are mentioned, they have been selected by the author on an objective basis to illustrate views expressed in the commentary and do not represent all of the securities purchased, sold or recommended for advisory clients. This material is intended solely for our clients and prospective clients, is for informational purposes only and is not individually tailored for or directed to any particular client or prospective client.
The information contained herein has been prepared from sources believed reliable but is not guaranteed by us as to its timeliness or accuracy and is not a complete summary or statement of all available data. The information in this document has not been independently reviewed or audited by outside certified public accountants. The information provided is not intended to be a forecast of future events or a guarantee of future results.
Terms and Definitions
Free cash flow (FCF) represents the cash a company generates after cash outflows to support operations and maintain its capital assets. Unlike earnings or net income, free cash flow is a measure of profitability that excludes the non-cash expenses of the income statement and includes spending on equipment and assets as well as changes in working capital.
Return on Invested Capital (ROIC) measures how much profit a company earns on its invested capital in a given year. It is calculated as a percentage of a company's net operating profit after tax divided by its average invested capital.
CapEx, or capital expenditures, are funds used by a company to acquire, upgrade, and maintain physical assets such as property, plants, buildings, technology or equipment.
Residual value is the estimated value of a fixed asset at the end of its lease term or useful life.
Credit risk is the risk that an issuer fails to make scheduled interest or principal payments in full and on time, potentially resulting in loss of value for bondholders. It increases as issuer fundamentals deteriorate (for example, rising leverage or weakening cash flows) and is embedded in broad bond benchmarks that include issuers regardless of changes in credit quality.
Downside protection refers to an investment approach or characteristic intended to help reduce potential losses during periods of market decline or adverse business conditions. It does not eliminate risk, prevent losses, or guarantee positive returns. The effectiveness of downside protection may vary depending on market conditions, portfolio positioning, security selection and other factors.
Epoch Capabilities Index (ECI) is a composite metric developed by Epoch AI that combines scores from dozens of different artificial intelligence benchmarks into a single, unified general capability scale